Financing a park home
Financing a manufactured home, with a partner who explains it plainly
Financing a manufactured home in a park is different from a traditional mortgage, and getting it right matters. We hand our buyers to Travis Olson, our mortgage partner, for pre-approval, loan options and the whole process in plain English.
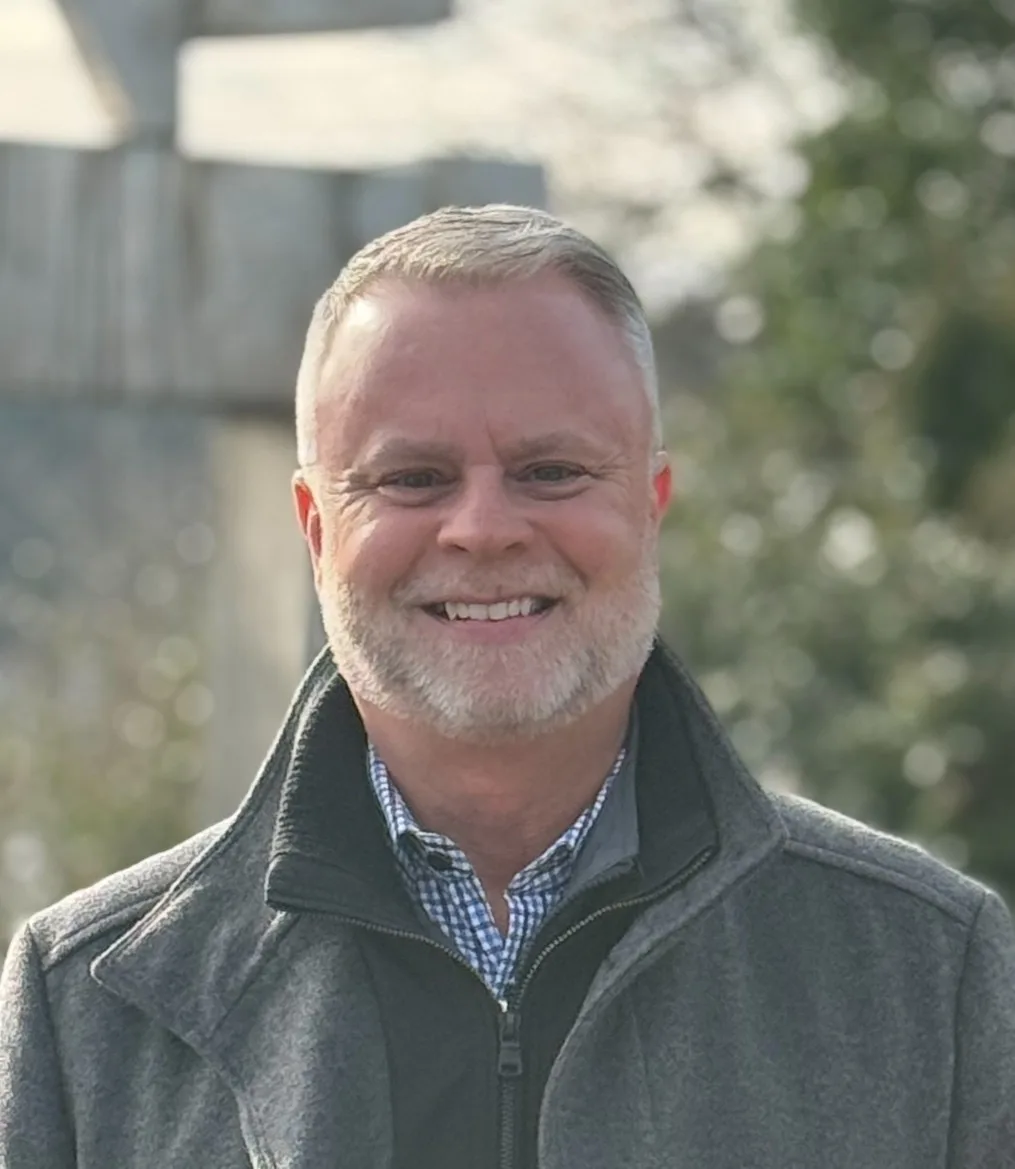
Meet our mortgage partner
Travis Olson
Mortgage Partner · Northwest Area Manager at Eureka Mortgage Planning
Travis is our mortgage partner and the person we hand buyers off to when their next step is financing. Based in Lake Oswego, Oregon, he guides buyers through pre-approval, loan options and the mortgage process with plain-English answers and no pressure. As Northwest Area Manager at Eureka Mortgage Planning, he works with a network of national and boutique lenders, so he can match you with the right program instead of pushing a single loan. He answers his own email.
Reach Travis directly
Email is the fastest way to reach him. No phone line, just a real person on the other end of the inbox.
tolson@eurekamortgage.net Visit Travis's websiteLoan programs
What Travis offers, built for manufactured-home buyers
Every program below is matched to your situation. Details and rates change, so ask for current pricing and program specifics for your purchase.
Manufactured & modular home financing
The core of what we do with Travis: financing for manufactured and modular homes, whether they sit in a park on leased land or come with the land underneath. Programs built for park homes, from roughly a 550 FICO score.
Pre-approval before you tour
Get a clear picture of your budget before you look at homes, so you tour with confidence and make offers that can actually close. This is the step that makes the whole search smoother.
Conventional, FHA, VA & USDA
A full menu of mainstream loan programs, matched to your situation and the type of purchase. Travis helps you compare which route makes sense rather than steering you to one product.
Down payment assistance
Options as low as 0% down through down payment assistance programs, for buyers who qualify. Ask for current pricing and program details for your situation.
New construction
Single-close construction/permanent financing for building a new manufactured or modular home, combining the construction loan and the permanent mortgage in one closing.
Non-QM options
For buyers who do not fit a conventional box: bank statement and DSCR loans, plus solutions for retirees, high-net-worth buyers and recent business owners. Ask Travis what fits.
How it works
The mortgage process, in six plain-English steps
No jargon, no pressure. Here is the path from application to keys, with Travis guiding you at every step.
- 1
Application
You start with a straightforward application. Travis keeps it plain-English and walks you through every field, so nothing feels like a test.
- 2
Documents
You gather the standard paperwork: income, assets and identity. Travis tells you exactly what is needed and what each document is for, with no surprises.
- 3
Pre-approval
Once your file is reviewed, you get a pre-approval that tells you what you can afford. This is the green light that makes touring and offers real.
- 4
Rate lock
When you are ready, Travis locks your rate so your payment is protected while the rest of the process moves forward.
- 5
Underwriting
The lender verifies your file in detail. Travis stays on top of it and answers questions as they come, so nothing stalls.
- 6
Closing
Final documents are signed, funds are released and you get the keys. Travis makes sure the numbers match what you agreed to.
Common questions
Financing questions, answered plainly
How is financing a park home different from a traditional mortgage?
It depends on the ground. When the home sits on leased park land, there is no owned land to mortgage, so buyers typically use chattel financing or programs built for park homes. When you own the land with the home, more traditional mortgage options are often available. Travis can map the right path for your situation.
What credit score do I need?
Many manufactured and modular home programs work from roughly a 550 FICO score, though your exact options depend on the program, the home and whether you own the lot. Ask Travis for current program details and pricing.
Can I buy with little or no money down?
Down payment assistance programs can offer options as low as 0% down, depending on your situation and the program. Ask for current pricing and qualification details.
Do you finance new construction?
Yes. New construction can be financed with single-close construction/permanent financing, which combines the construction loan and the permanent mortgage in one closing. Ask Travis for current program details.
What if I do not fit a conventional loan?
Non-QM options are available, including bank statement loans, DSCR loans, and solutions for retirees, high-net-worth buyers and recent business owners. Ask Travis which program fits your situation.
Ready to talk financing?
Email Travis directly and he will answer himself, with plain-English guidance and no pressure. Tell him where you are in the process and what you are hoping to buy, and he will point you to the right next step.
Our team is here too
Paul and Troy are happy to connect you with Travis and to help with the whole park-home search. Reach the team at the Meridian office during business hours.
- MORE Realty, 3597 Monarch Sky Lane #240, Meridian, ID 83642
- Mon-Fri 9:00 AM to 5:00 PM, after hours by appointment. Please call or text.